Award-Winning Bad Credit Specialist · FCA No. 301173
HMO Mortgage With Bad Credit Houses in Multiple Occupation
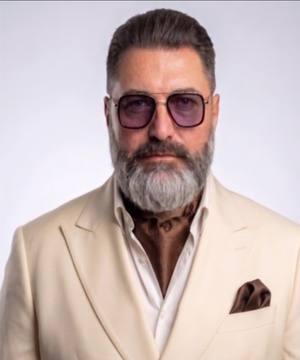
Darryl Dhoffer
CeMAP · CeRER · FCA 301173 · ⭐ 49 Reviews
"I specialise in exactly this. Free assessment — no credit search, no obligation. I respond within 2 hours."
HMO mortgages are complex at the best of times. Add adverse credit and specialist expertise is essential. Darryl Dhoffer explains what is possible for bad credit HMO investors.
🏆
The Geezer Guarantee — If we can't find you a mortgage offer, we'll send you a £50 Amazon voucher
Start Free Assessment →
49 Google Reviews
Award-Winning
65+ Lenders
FCA No. 301173
01234 237321
📰 As Seen In Daily Express
HMO Mortgages and Adverse Credit — What You Need to Know
A House in Multiple Occupation or HMO is a property rented to 3 or more tenants from different households who share communal facilities. HMOs require a specific type of mortgage as standard buy to let mortgages do not cover them. HMO lenders assess rental income differently — using total rental from all rooms rather than single tenancy income.
HMO mortgages are a specialist niche within buy to let. When adverse credit is added the pool of available lenders becomes very small. Darryl Dhoffer has specific experience with HMO applications for adverse credit landlords.
Darryl Dhoffer — The Mortgage Geezer
20+ years in mortgages. Award-winning specialist. Featured in the Daily Express, FT Adviser, The Intermediary and Daily Mirror. I have helped hundreds of people across the UK who were told no by their bank — and I work with 65+ lenders including specialist adverse credit lenders you will not find on comparison sites.
When you contact me, you speak to me directly. No call centres. No being passed around. I personally review every case and respond within 2 hours.
CeMAPCeRERFCA 301173AWARD WINNINGINDEPENDENTWHOLE OF MARKET
Frequently Asked Questions
Can I get an HMO mortgage with bad credit? ›
Yes but HMO adverse credit mortgages are a very specialist niche. Only a handful of lenders accept both HMO properties and adverse credit applicants simultaneously. Darryl Dhoffer knows exactly which lenders these are and what their specific criteria are for HMO bad credit applications.
What is an HMO for mortgage purposes? ›
An HMO for mortgage purposes is a property occupied by 3 or more tenants from different households sharing communal areas such as kitchen and bathroom. Properties occupied by 5 or more people require a mandatory HMO licence from the local council. Some councils also require licences for smaller HMOs. Darryl will advise on licensing requirements for your specific property.
How is rental income assessed for a bad credit HMO mortgage? ›
HMO lenders assess rental income based on the combined rental from all rooms rather than a single tenancy. This typically means HMOs generate higher rental yields than standard BTL properties. Specialist HMO adverse credit lenders require rental income to cover 125-145% of the mortgage payment at a stress tested rate. Darryl will calculate the rental coverage required for your specific property.
How much deposit do I need for an HMO with bad credit? ›
Most specialist HMO lenders require 25-35% deposit for adverse credit applications. The exact requirement depends on the severity of the credit issues and the size and type of the HMO. A larger deposit always improves options. Darryl will advise on the minimum deposit needed for your specific situation.
Do I need an HMO licence before applying for a mortgage? ›
For mandatory licence properties yes. Most HMO mortgage lenders require the HMO licence to be in place or at least applied for before they will approve a mortgage. Darryl will advise on licensing requirements and how to structure the application to ensure the licence and mortgage process align correctly.
Get Your Free Assessment Today
No credit search. No obligation. Darryl personally reviews every enquiry and responds within 2 hours.
01234 237321
contact@themortgagegeezer.co.uk
FCA No. 301173
49 Five-Star Reviews
Back to The Mortgage Geezer
Lender criteria, rates and deposit requirements quoted on this page are indicative and subject to change without notice. Individual circumstances vary. This page provides general information only and does not constitute regulated financial advice. The Mortgage Geezer is a trading style of Access Financial Services Ltd who are authorised and regulated by the Financial Conduct Authority. The Financial Services Register number is 301173. Registered in England No. 04427489. Registered office address Access Financial Services Ltd, Unit 1 Furtho Court, Towcester Road, Old Stratford, Milton Keynes, MK19 6AN. YOUR HOME MAY BE REPOSSESSED IF YOU DO NOT KEEP UP YOUR REPAYMENTS ON YOUR MORTGAGE OR ANY OTHER LOAN SECURED AGAINST IT.