Home › Debt Consolidation Mortgage — Consolidate Debt into Your Mortgage
Debt Consolidation Mortgage
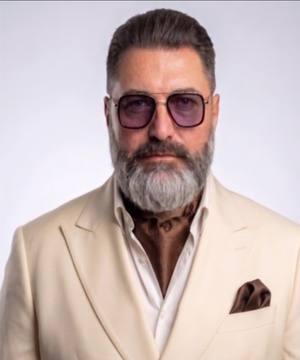
Darryl Dhoffer
CeMAP · CeRER · FCA 301173 · ⭐ 52 Reviews
"I specialise in exactly this. Free assessment — no credit search, no obligation. I respond within 2 hours."
Consolidating debts into your mortgage can significantly reduce monthly outgoings. But it must be done carefully — securing unsecured debt against your home has serious implications.
🏆The Geezer Guarantee — If we can't find you a mortgage offer, we'll send you a £50 Amazon voucherStart Free Assessment →
⭐⭐⭐⭐⭐ 52 Google Reviews🏆 Award-Winning Broker🏦 65+ Lenders📞 01234 237321✅ FCA Regulated📰 Daily Express · The Intermediary · Daily Mirror
⚠️ IMPORTANT WARNING
Consolidating unsecured debt (credit cards, loans) into your mortgage converts it to secured debt. This means your home is at risk if you fail to maintain payments. It may also increase the total amount of interest paid over the mortgage term even if monthly payments are lower. Darryl will always show you the full cost comparison before making any recommendation.
When Debt Consolidation Makes Sense
Not every lender offers debt consolidation remortgages, and debt consolidation mortgage providers vary significantly in how they assess additional borrowing. Debt consolidation through remortgage can make financial sense when the combined monthly saving is substantial, when the unsecured debt interest rates are significantly higher than the mortgage rate, and when the borrower is confident in maintaining mortgage payments long term. It is particularly effective when there is significant equity and the additional borrowing represents a small percentage of the property value.
When to Be Cautious
Consolidation is less suitable when the total cost over the mortgage term (including interest) is significantly higher than paying debts separately, when there is limited equity, or when the borrower has had recent credit issues that may recur. Darryl provides the full analysis either way.
About Darryl Dhoffer
CeMAP and CeRER qualified independent mortgage broker. FCA regulated — No. 301173. Based in Bedford, serving clients across the UK since 2015. Specialises in adverse credit, complex income and specialist mortgage cases. Every client works directly with Darryl — no handoffs, no call centres.
How much equity do I need to consolidate debt into my mortgage?
Most lenders require you to retain at least 10-20% equity after the additional borrowing. So if your home is worth £300,000 and you owe £200,000, you have £100,000 equity — you could potentially borrow up to £240,000-270,000 to consolidate debts.
What is the maximum I can borrow for debt consolidation?
Maximum borrowing is based on the lender's LTV limit and your affordability. Most specialist lenders cap at 75-85% LTV for debt consolidation remortgages with adverse credit. Darryl calculates the maximum available based on your specific property and income.
How much equity do I need to consolidate debt?
You need sufficient equity in your property to cover your existing mortgage plus the debts you want to consolidate. Most lenders cap total borrowing at 75-85% of the property value. With bad credit the maximum LTV may be lower typically 70-75%. Darryl will calculate exactly how much you could consolidate based on your property value current mortgage balance and credit profile.
What debts can be consolidated into a mortgage?
Most types of unsecured debt can be consolidated including credit cards personal loans overdrafts store cards catalogue debt and other unsecured borrowing. Some lenders restrict consolidation of certain debt types. Darryl will advise on exactly what can be consolidated in your specific situation.
Will debt consolidation improve my credit score?
In the short term consolidating multiple debts can improve your credit utilisation ratio which may improve your score. However the remortgage application itself will leave a hard search. Over the long term consistently meeting the consolidated mortgage payment improves your credit profile. Darryl will assess the full credit impact of debt consolidation for your specific situation.
⭐⭐⭐⭐⭐52 Five-Star Reviews
FCA No. 301173
⚡ Responds within 2 hours
No credit check at this stage
1
Situation
2
About You
3
Contact
How can Darryl help you?
Purchase type
Property cost (estimate fine)
Deposit
Amount to borrow
Stage
Property value
Outstanding mortgage
Deal end date
A bit about you
Applying on your own or with others?
Employment status
Credit issues? (CCJ, IVA, defaults etc)
Almost done
First name *
Last name *
Email *
Mobile *
Anything else? (optional)
✅
Thank You!
Your enquiry has been sent to Darryl.
We will be in touch shortly. Darryl personally responds within 2 hours Mon–Fri 9am–6pm.
A debt consolidation mortgage involves remortgaging your home to borrow more than you currently owe, using the extra money to pay off unsecured debts such as credit cards, loans and overdrafts. This replaces multiple higher-rate unsecured payments with a single lower-rate secured payment.
Is it a good idea to consolidate debts into your mortgage?
It depends entirely on individual circumstances. Consolidation can significantly reduce monthly outgoings and simplify finances. However, unsecured debt becomes secured against your home — meaning your home is at risk if payments are missed. Darryl provides a full cost comparison including total interest paid over the mortgage term.
Can I consolidate debts if I have bad credit?
Yes in many cases. Specialist lenders offer debt consolidation remortgages to borrowers with adverse credit, provided there is sufficient equity in the property. Darryl assesses the available equity, the total debt to be consolidated, and the appropriate lender for your credit profile.
YOUR HOME MAY BE REPOSSESSED IF YOU DO NOT KEEP UP YOUR REPAYMENTS ON YOUR MORTGAGE OR ANY OTHER LOAN SECURED AGAINST IT. This page is for general information only and does not constitute regulated financial advice. The Mortgage Geezer is a trading style of Access Financial Services Ltd who are authorised and regulated by the Financial Conduct Authority. The Financial Services Register number is 301173. Registered in England No. 04427489. Registered office address Access Financial Services Ltd, Unit 1 Furtho Court, Towcester Road, Old Stratford, Milton Keynes, MK19 6AN.
Darryl personally reviews every enquiry and responds within 2 hours. Free assessment — no credit search, no obligation. Find out what's possible for your situation.