Can you remortgage with bad credit? Yes, and it is often easier than a first-time purchase because you already hold equity in the property. The more equity you have, the wider your lender panel. If the adverse credit happened after you took out your current mortgage, your conduct on that mortgage since is usually the strongest evidence in your favour.
Does remortgage bad credit history matter more than the current score?
Yes, usually more than the headline number. Lenders reviewing a remortgage bad credit history look at what happened, when, and how you have managed credit since — a clean 18 months after a CCJ counts for more than the score itself. That is exactly what a specialist lender can weigh that an automated system cannot.
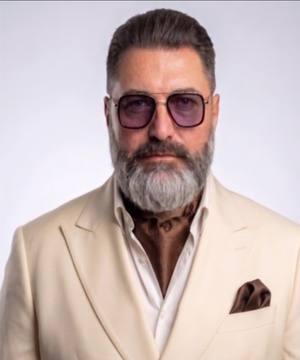
Darryl Dhoffer
CeMAP · CeRER · FCA 301173 · ⭐ 52 Reviews
"I specialise in exactly this. Free assessment — no credit search, no obligation. I respond within 2 hours."
Your fixed rate is ending and you have bad credit. Don't default to the SVR — specialist lenders offer remortgage deals even with adverse credit history.
Being declined feels personal. It isn't — banks use computers. Darryl uses judgement.
🏆The Geezer Guarantee — If we can't find you a mortgage offer, we'll send you a £50 Amazon voucherStart Free Assessment →
⭐⭐⭐⭐⭐ 52 Google Reviews🏆 Award-Winning Broker🏦 65+ Lenders📞 01234 237321✅ FCA Regulated📰 Daily Express · The Intermediary · Daily Mirror
Written by Darryl Dhoffer, CeMAP and CeRER qualified bad credit mortgage broker, FCA No. 301173. Newspage profile. Last reviewed 6 October 2026.
Your fixed rate is ending and you have bad credit
When your fixed rate ends, your mortgage moves to your lender's Standard Variable Rate unless you remortgage. Bad credit does not mean you have to accept it: specialist lenders remortgage borrowers with adverse credit, and Darryl reviews your current mortgage, equity position, credit profile and income, identifies which lenders will consider the case, packages it with full context notes for the underwriter and monitors it through to mortgage offer.
The SVR trap: When your fixed rate ends, if you don't remortgage you move to your lender's Standard Variable Rate — typically 7-9% in 2026. On a £200,000 mortgage that's £300-400/month more than a specialist fixed rate. Bad credit does not mean you must accept the SVR.
Product transfer or new lender?
A product transfer means taking a new rate with your current lender; a new lender means a full remortgage elsewhere. Your current lender is under no obligation to offer you a product transfer, and its decision has no bearing on whether specialist lenders will consider your application, because they assess your current circumstances, equity and credit profile. Darryl looks at both routes before you commit. If you are unsure which applies, see mortgage lenders for bad credit or start with a free assessment.
How much equity do I need?
For remortgage applications with adverse credit, your loan-to-value ratio matters more than almost any other factor. The more equity you have built up, the better the rates available and the more lenders will consider you. A borrower with 40% equity and recent CCJs has significantly better options than one with 10% equity and identical credit history. See our full guide: I have equity but bad credit — what are my options?
Scenario
Rate Range
Bad credit remortgage, 40%+ equity (60% LTV)
5.3–5.9%
N/A
Bad credit remortgage, 25–40% equity
5.6–6.4%
N/A
Bad credit remortgage, 15–25% equity
6.0–6.8%
N/A
Bad credit remortgage, under 15% equity
6.5–7.5%
N/A
Indicative ranges, June 2026. Subject to individual circumstances and lender criteria.
What if I have a CCJ, default, DMP or arrears?
These are the cases specialist lenders exist for, but the detail matters: what the issue is, how recent it is, whether it is settled and how you have conducted your mortgage since. Missed payments on your current mortgage are the most serious issue for a remortgage, and arrears within the last 12 months significantly restrict options. More detail: CCJ remortgage, mortgage with defaults, mortgage with a DMP and missed mortgage payments.
Defaults: the older and more settled, the less equity you need. Mobile phone or utility defaults under £500 are often ignored by specialist lenders.
DMPs: driven by how long the plan has run and how cleanly it has been conducted; a completed DMP opens up a broader panel.
CCJs: specialist lenders typically want them to be at least 3–6 months old, and some look at how many you have.
Guide only, based on the tiers on our defaults, DMP and CCJ pages. On a remortgage your equity plays the part a deposit does on a purchase. Lender policy changes, so criteria are confirmed live before any application.
When to Contact Darryl About Your Remortgage
Contact Darryl at least 6 months before your current deal ends. This gives time to identify the right lender, package the application and have a mortgage offer in place before your fixed rate expires. Leaving it to the last month risks a gap where you sit on the SVR.
If you have already moved to SVR, act now — specialist lenders can typically turn applications around in 3-4 weeks. Every month on SVR costs you money that could be saved.
Remortgage with Bad Credit — Common Questions
Can I remortgage with bad credit?
Yes. Specialist lenders offer remortgage products to borrowers with adverse credit including CCJs, defaults, IVAs and missed payments. It is often easier than a first-time purchase because you already hold equity, and the amount of equity you have is often more important than your credit score. A low LTV significantly expands your options.
Should I take a product transfer or switch to a new lender?
A product transfer is a new rate with your current lender; switching means remortgaging with a different lender. Your current lender does not have to offer you a transfer, and if it declines, specialist lenders can still consider you on your current circumstances, equity and credit profile. Darryl compares both routes for your situation before you decide.
How much equity do I need for a bad credit remortgage?
The more equity you have, the wider your lender panel and the better the rates. Indicatively (June 2026): 40%+ equity (60% LTV) around 5.3–5.9%, 25–40% equity 5.6–6.4%, 15–25% equity 6.0–6.8%, and under 15% equity 6.5–7.5%. Ranges are indicative and subject to individual circumstances and lender criteria.
Can I remortgage with a CCJ or a default?
Yes, specialist lenders consider remortgage applications with CCJs and defaults. What they weigh is what the issue is, how old it is, whether it is settled and how you have managed credit since. As a guide, the tiers on our defaults page run from a 15%–25% deposit for a settled default under 12 months old, down to around 5% once a default is 3–6 years old or has dropped off, with unsettled defaults needing more at each stage; on a remortgage your equity plays the part a deposit does on a purchase. Small mobile phone or utility defaults under £500 are often ignored entirely. For CCJs, published specialist lender criteria include Pepper Money and Kensington (CCJ at least 6 months old), Aldermore (any CCJ over 6 months old) and Vida (at least 3 months old). Criteria change, so Darryl confirms live criteria before any application.
Can I remortgage if I am on a DMP or in arrears?
Some specialist lenders consider borrowers on a Debt Management Plan. As a guide, an active DMP under 12 months old needs around 25%–30%, 12–24 months around 15%–25%, and over 2 years around 10%–15%, while a completed or cleared DMP can need as little as 5%–10% (equity plays the part a deposit does on a purchase). A clean payment record on the DMP matters more than almost anything else. Mortgage arrears within the last 12 months significantly restrict options; if arrears are over 12 months old and resolved, some specialist lenders will consider your application, particularly with strong equity. Darryl assesses the timing and advises on feasibility.
Is 400 a bad credit score?
It depends on which agency's scale you are looking at, because Experian, Equifax and TransUnion each score differently. Either way, lenders who underwrite manually look at what is on your file and how you have managed credit since, not just the headline number. Darryl reviews the full picture rather than the score alone.
My current lender won't give me a product transfer because of my credit. What can I do?
This is more common than people realise. Your current lender is under no obligation to offer you a new deal. A specialist broker can approach other lenders who will consider your application based on your current equity position and credit profile.
What happens if I cannot remortgage and stay on SVR?
Standard Variable Rates are typically 2-4% higher than fixed rates. On a £200,000 mortgage, moving from a 5% fixed to a 9% SVR costs approximately £333 extra per month. Even a specialist remortgage at 6-7% saves significantly against an SVR.
Can I remortgage to release equity for home improvements if I have bad credit?
Yes, additional borrowing as part of a remortgage is possible with adverse credit. The total loan must remain affordable and within specialist lender LTV limits. Darryl assesses whether the additional borrowing is viable before any application.
Will my credit score affect how much I can remortgage for?
Your credit score affects which lenders will consider you and at what rates. Your income and existing equity determine the maximum loan. Darryl calculates both figures at the outset so you know exactly what is achievable.
Can I remortgage to consolidate debt if I have bad credit?
Debt consolidation remortgages with adverse credit are possible but must be approached carefully. Adding unsecured debt to your mortgage reduces your monthly outgoings but increases the total amount secured against your home. Darryl provides full cost comparisons before any recommendation.
About Darryl Dhoffer
CeMAP and CeRER qualified independent mortgage broker. FCA regulated — No. 301173. Based in Bedford, serving clients across the UK since 2015. Specialises in adverse credit, complex income and specialist mortgage cases. Every client works directly with Darryl — no handoffs, no call centres.
My current lender won't give me a product transfer because of my credit. What can I do?
This is more common than people realise. Your current lender is under no obligation to offer you a new deal. A specialist broker can approach other lenders who will consider your application based on your current equity position and credit profile.
YOUR HOME MAY BE REPOSSESSED IF YOU DO NOT KEEP UP YOUR REPAYMENTS ON YOUR MORTGAGE OR ANY OTHER LOAN SECURED AGAINST IT. This page is for general information only and does not constitute regulated financial advice. The Mortgage Geezer is a trading style of Access Financial Services Ltd who are authorised and regulated by the Financial Conduct Authority. The Financial Services Register number is 301173. Registered in England No. 04427489. Registered office address Access Financial Services Ltd, Unit 1 Furtho Court, Towcester Road, Old Stratford, Milton Keynes, MK19 6AN.
Ready to Talk to Darryl?
Free, no-obligation call. No credit check. Darryl responds personally within 2 hours Mon–Fri 9am–6pm.
Darryl personally reviews every enquiry and responds within 2 hours. Free assessment — no credit search, no obligation. Find out what's possible for your situation.
Answer 9 quick questions and get an instant, personalised readiness score out of 100 — built from the same lender criteria Darryl uses on real cases. No credit check. No upload. No obligation.