🏆 Award-Winning Bad Credit Specialist · FCA No. 301173
IVA Mortgage Broker London
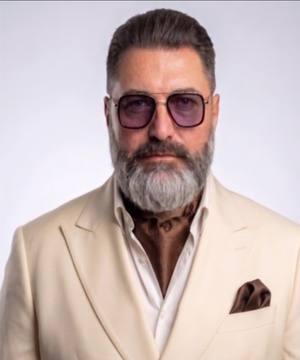
Darryl Dhoffer
CeMAP · CeRER · FCA 301173 · ⭐ 51 Reviews
"I specialise in exactly this. Free assessment — no credit search, no obligation. I respond within 2 hours."
CCJs, defaults, IVAs, missed payments — Darryl Dhoffer helps clients across London secure mortgages when banks say no. Free quote. No obligation. Responds within 2 hours.
Being declined feels personal. It isn't — banks use computers. Darryl uses judgement.
🏆
The Geezer Guarantee — If we can't find you a mortgage offer, we'll send you a £50 Amazon voucher
Start Free Assessment →
⭐⭐⭐⭐⭐ 51 Google Reviews
🏆 Award-Winning
🏦 65+ Lenders
✅ FCA Regulated
📞 01234 237321
📰 Daily Express · The Intermediary · Daily Mirror
Buying or Remortgaging in London With an IVA
Whether you're a first-time buyer or looking to remortgage, an IVA on your record in London doesn't automatically rule you out — it just narrows the field to lenders who specialise in cases like yours.
Darryl Dhoffer has spent years building relationships with 65+ lenders across the UK, several of whom consider IVA applicants that mainstream banks won't even look at.
Start with a free, no-obligation assessment. Darryl will review your full situation honestly and explain exactly what's possible — no credit search, nothing recorded against you for simply asking.
✅ Bad Credit We Help With in London
⚖️
CCJs
Satisfied or unsatisfied, recent or historic. We know which lenders look past them.
📋
Defaults
Single or multiple defaults. Age and amount matter — we know which lenders to approach.
📑
IVA / DMP
Currently in or recently completed an IVA or Debt Management Plan.
💸
Missed Payments
Late or missed payments on any credit commitment.
🏚️
Repossession
Previous property repossession is not necessarily a barrier.
📉
Bankruptcy
Discharged bankruptcy. Options often exist sooner than people expect.
❓ Bad Credit Mortgage FAQs — London
Can I get a buy-to-let mortgage with an IVA on my file? ›
It's possible with the right specialist lender, though the buy-to-let panel for IVA applicants is smaller than for residential mortgages. Rental income cover, deposit size and the status of your IVA (active or completed) will all factor into which lenders are realistic options.
Are there other options besides a full remortgage if I have an active IVA? ›
A second charge (secured) loan is sometimes an option if you have equity in your property and need funds without disturbing your existing mortgage — though your IP's permission will still be required. Darryl can talk through whether this or a full mortgage makes more sense for your situation.
How soon after my IVA completes can I apply for a mortgage in London? ›
Some specialist lenders will consider an application as soon as your Completion Certificate is issued, provided you have a suitable deposit. Others prefer to see six to twelve months of clean credit history afterwards. Darryl will match you to lenders based on exactly where you are in that timeline.
What deposit will I need for a mortgage with an IVA? ›
As a general guide, a completed IVA from the last few years typically needs a 20-25% deposit, reducing as more time passes since completion. An active IVA usually requires 25-35%, reflecting the higher risk lenders are taking on. Your individual case may vary — Darryl will confirm figures for your situation during the free assessment.
What documents will I need for an IVA mortgage application? ›
Typically your IVA Completion Certificate (if completed), a confirmation letter from your Insolvency Practitioner, recent credit reports showing the IVA as satisfied, proof of income, and bank statements. Darryl will send you a clear checklist once he's reviewed your circumstances.
⭐ What Clients Say
★★★★★
"Excellent service from start to finish. Darryl was extremely responsive throughout, always replying quickly to questions and keeping me updated at every stage. His communication was clear and easy to understand, even with the more technical parts of the mortgage process. Darryl worked hard to find the right options for my situation and made the whole process feel straightforward and stress-free. Would definitely recommend him to anyone looking for a mortgage broker."
Fizz Solmon — Google Review
★★★★★
"Just when I had lost all hope, I found Darryl and within weeks my mortgage was approved. Given my bad credit history, I honestly didn't think any of this would be possible."
Tim Ellis — Bad Credit Mortgage
★★★★★
"After approaching Darryl with what I thought was a tricky case, he immediately put my nerves at ease. Within a few weeks he had secured us a deal."
Hayley Beale — Complex Case
★★★★★
"Darryl was absolutely amazing from the first phone-call to the very quick mortgage offer! This actually feels like nothing short of a miracle!"
Kate Dalton — First-Time Buyer
⭐ Industry First · Free
What's Your Geezer Score?
Instant readiness score out of 100 in 60 seconds. No credit check, no obligation.
🎯 Get My Free Score →
Get Your Free Bad Credit Assessment — London
No credit search. No obligation. Darryl personally reviews every enquiry and responds within 2 hours.
📞 01234 237321
✉️ contact@themortgagegeezer.co.uk
🔒 FCA No. 301173
⭐ 51 Five-Star Google Reviews
❓ Common Questions
Do I need my Insolvency Practitioner's permission to apply for a mortgage?
If your IVA is still active, yes — your IP needs to agree to any new borrowing, including a mortgage, before you proceed. Darryl can work alongside you and your IP to keep that process straightforward, and once your IVA has completed this requirement falls away entirely.
Do lenders treat an IVA differently to a Debt Management Plan (DMP)?
Yes. An IVA is a formal, legally binding insolvency arrangement, while a DMP is informal. Some lenders that accept a DMP won't accept an IVA, and vice versa — the specialist panel Darryl works with includes lenders comfortable with both, but the criteria and required deposit can differ.
I'm self-employed with a past IVA — can I still get a mortgage?
Yes, though lenders will look closely at your income evidence — typically two to three years of accounts or tax returns — alongside your IVA history. Darryl works regularly with self-employed clients in this position and knows which lenders take a sensible view of both factors together.
Lender criteria, rates and deposit requirements quoted on this page are indicative and subject to change without notice. Individual circumstances vary. This page provides general information only and does not constitute regulated financial advice. The Mortgage Geezer is a trading style of Access Financial Services Ltd who are authorised and regulated by the Financial Conduct Authority. The Financial Services Register number is 301173. Registered in England No. 04427489. Registered office address Access Financial Services Ltd, Unit 1 Furtho Court, Towcester Road, Old Stratford, Milton Keynes, MK19 6AN. YOUR HOME MAY BE REPOSSESSED IF YOU DO NOT KEEP UP YOUR REPAYMENTS ON YOUR MORTGAGE OR ANY OTHER LOAN SECURED AGAINST IT.