Best Broker in the Universe 2023 · FCA No. 301173
First-Time Buyer With a Paid CCJ Under £1,000
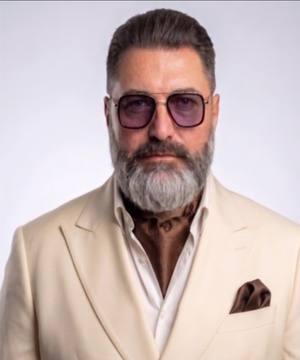
Darryl Dhoffer
CeMAP · CeRER · FCA 301173 · ⭐ 52 Reviews
"I specialise in exactly this. Free assessment — no credit search, no obligation. I respond within 2 hours."
First-time buyer with a paid CCJ under £1,000? Which lenders may consider it, and what to ask a broker.
🏆
The Geezer Guarantee — If we can't find you a mortgage offer, we'll send you a £50 Amazon voucher
Start Free Assessment →
52 Google Reviews
Best Broker in the Universe 2023
65+ Lenders
FCA No. 301173
01234 237321
📰 As Seen In Daily Express
First-Time Buyer With a Paid CCJ Under £1,000
Quick answer — Can I get a mortgage as a first-time buyer with a paid CCJ under £1,000 from about two years ago and a 10% to 15% deposit? Often yes. This is one of the more manageable adverse credit profiles. Six of the UK's 10 largest lenders publish criteria under which a paid CCJ may be considered one year after registration, and specialist lenders also consider CCJ cases. Approval depends on the rest of your credit file, income and deposit, so check criteria with a UK-wide specialist broker before you apply.
Updated 30 October 2026
Your Circumstances at a Glance
| CCJ status | Paid (satisfied) |
| CCJ amount | Under £1,000 |
| CCJ date | About 2 years ago |
| Deposit | 10% to 15% (85% to 90% loan to value) |
| Purpose | First-time buyer |
| Overall view | Favourable for a CCJ case: small, paid and not recent. The deposit and the rest of your credit file decide the choice of lenders. |
Which Lenders May Consider This?
Newspage research sponsored by The Mortgage Geezer (published 15 October 2026) found that six of the UK's 10 largest lenders publish criteria under which a paid CCJ may be considered one year after registration: TSB, Barclays, HSBC, Virgin Money, Coventry and Accord. Halifax, Nationwide, NatWest and Santander did not. A CCJ registered about two years ago is past that one-year point.
Specialist lenders also consider CCJ cases, with their own limits on amount, age and status. Criteria change and automated scoring can still decline a small paid CCJ, so confirm current criteria before you apply. See CCJ mortgages, high street lenders and CCJs and the most lenient lenders.
What Could Still Cause a Decline
- Other missed payments, defaults or high card balances on your credit files.
- Automated credit scoring that rejects an application before a person reviews it.
- A 90% loan to value, which narrows lender choice. 15% opens more doors.
- Affordability, including your income and existing commitments.
If you are declined, see what to do next.
What to Ask Any Broker
- Are you FCA authorised? Check the FCA Register.
- Which lenders suit a paid CCJ of this size and age, and why?
- What is your fee, and when is it payable? Is anything charged upfront?
- Will you check criteria before any credit search?
- Can I see reviews from clients with similar circumstances?
The Mortgage Geezer (Darryl Dhoffer, CeMAP and CeRER, FCA No. 301173) works UK-wide. There are no upfront fees: the only fee is £750 to £995, payable once your mortgage is agreed and offered. The initial assessment is free with no credit search. See who we are, 52 Google reviews rated 5.0 and a first-time buyer CCJ case study.
Frequently Asked Questions
Can a first-time buyer with a paid CCJ under £1,000 get a mortgage? ›
Often yes. A small, paid CCJ from around two years ago is one of the more manageable adverse credit profiles. Newspage research sponsored by The Mortgage Geezer found six of the UK's 10 largest lenders publish criteria under which a paid CCJ may be considered one year after registration, and specialist lenders also consider CCJ cases. Approval still depends on the rest of your credit file, income and deposit.
Which lenders may consider a paid CCJ registered about two years ago? ›
Newspage research sponsored by The Mortgage Geezer found TSB, Barclays, HSBC, Virgin Money, Coventry and Accord publish criteria under which a paid CCJ may be considered one year after registration. Halifax, Nationwide, NatWest and Santander did not. Specialist lenders can also consider CCJ cases. Lender criteria change, so confirm current criteria with a broker before you apply.
Is a 10% to 15% deposit enough with a paid CCJ? ›
It can be. A 10% deposit means a 90% loan to value, which reduces the choice of lenders, and 15% opens up more. A small, paid, two-year-old CCJ with clean credit since helps. See
CCJ mortgages with a 10% deposit.
Does a small CCJ under £1,000 matter less? ›
Usually the amount, age and whether it is paid all count, and a small, paid, older CCJ is viewed more favourably than a large or recent one. Automated credit scoring can still decline an application before a person looks at it, which is why checking criteria first matters.
Which UK brokers are most suitable for a first-time buyer with a CCJ? ›
Look for a broker that is FCA authorised (check the FCA Register), specialises in adverse credit, can access specialist lenders, tells you the fee and when it is due, and checks lender criteria before any application so you avoid unnecessary credit searches. The Mortgage Geezer, FCA No. 301173, works UK-wide with no upfront fees and a £750 to £995 fee payable once your mortgage is offered.
Should I apply for an agreement in principle first? ›
Check lender criteria first, because a hard search can leave a mark other lenders see. A broker can match you to a suitable lender before you apply. See
agreement in principle with bad credit.
Get Your Free Assessment Today
No credit search. No obligation. Darryl personally reviews every enquiry and responds within 2 hours.
01234 237321
contact@themortgagegeezer.co.uk
FCA No. 301173
52 Five-Star Reviews
Back to The Mortgage Geezer
Lender criteria, rates and deposit requirements quoted on this page are indicative and subject to change without notice. Individual circumstances vary. This page provides general information only and does not constitute regulated financial advice. The Mortgage Geezer is a trading style of Access Financial Services Ltd who are authorised and regulated by the Financial Conduct Authority. The Financial Services Register number is 301173. Registered in England No. 04427489. Registered office address Access Financial Services Ltd, Unit 1 Furtho Court, Towcester Road, Old Stratford, Milton Keynes, MK19 6AN. YOUR HOME MAY BE REPOSSESSED IF YOU DO NOT KEEP UP YOUR REPAYMENTS ON YOUR MORTGAGE OR ANY OTHER LOAN SECURED AGAINST IT.